09 Sep 2026 · Chirag Asnani
Rentomojo: India's First Listed Rental Play — Good Company, Fair Value?
For the first time, Indian public markets get to price a furniture-and-appliance rental platform. Rentomojo Limited opens its ₹1,256 crore IPO in a ₹384–404 band, valuing the company near ₹4,250 crore at the top. It arrives with something most new-age listings have lacked — real profit — but also with a price tag that already asks a lot. The useful question is not "will it list well?" It is the one a serious investor actually cares about: is this a good business, growing well, offered at a fair value — or two out of three?
The business: renting, not owning
Rentomojo rents home furniture and large appliances — beds, sofas, refrigerators, washing machines, televisions — on monthly subscriptions instead of owning them outright. The company owns the asset, refurbishes it and re-rents it across several tenures, so a single unit can earn for years. It is India's largest such platform by revenue, with 253,825 live subscribers (up from ~149,000 two years earlier), roughly 50% repeat orders, and 82 experience stores across 17 cities. Furniture and appliances split the book almost evenly, and rentals are ~98% of revenue.
The market behind it is real but not enormous: India's organised furniture-rental opportunity is estimated near ₹33,500 crore, growing about 11% a year, concentrated in the top cities where young, mobile, salaried renters cluster (average ticket ~₹1,900 a month, typical tenure ~13 months). That concentration is both the moat and the ceiling — it is where the demand is, and also where Rentomojo has already done most of its scaling.
The growth and the profit are real — with an asterisk
On the surface the numbers are excellent. Revenue rose 42% in FY26 to ₹387 crore, EBITDA margins run near 41%, and return on net worth is a headline 43.5%. Very few consumer-internet businesses reach the market already generating cash. So the "good company, good growth" half of the question largely answers itself: this is a genuine, expanding franchise with improving cost ratios.
Two asterisks matter, though, and both flatter the optics. First, this is an asset-heavy model: the rented goods wear out, so a large slice of that 41% EBITDA is consumed by depreciation (~₹70 crore in FY26). EBITDA is not free cash here the way it is for an asset-light software name — the "cost of goods" simply arrives later, as depreciation and replacement. Second, FY26 profit was lifted by a one-time deferred-tax credit (the company recognised deferred-tax assets). Strip that out and normalised profit is closer to ₹68 crore than the reported ₹104 crore — which, as we will see, changes the multiple materially.
Who is cashing out, and what the money funds
The offer structure is the most telling part. Of the ₹1,256 crore, only ₹150 crore is fresh capital for the company; the remaining ~88% is an Offer for Sale by early venture investors — Accel, IDG, Edelweiss, Chiratae and others — who invested at a weighted-average cost of roughly ₹47–82 against a ₹384–404 band. That is not a criticism; a decade-old fund realising a 5–10x return is doing exactly its job. But an investor should be clear that the vast majority of their money goes to existing shareholders exiting, not into growth. The small fresh portion is earmarked for repaying borrowings, and for warehouses and experience stores.
What has no listed peer is hard to price
Rentomojo's prospectus states plainly that there is no comparable listed company in India or globally — so the multiple has to justify itself rather than lean on a peer average. At ₹404 the stock is offered at roughly:
| Measure | At ₹404 (cap) | Context |
|---|---|---|
| P/E (FY26, reported) | ~40x | flattered by the deferred-tax credit |
| P/E (FY26, normalised) | ~60x | on ~₹68 cr underlying profit |
| EV / EBITDA (FY26) | ~27x | but EBITDA is pre-depreciation on wearing assets |
| Market cap / sales | ~11x | on ₹387 cr revenue |
To frame fair value without a direct peer, it helps to bracket the business between the two worlds it straddles. Profitable, high-growth consumer platforms in India have at times commanded 40–60x earnings; asset-heavy rental, leasing and consumer-finance businesses — which is what the balance sheet actually resembles — typically trade in the low-to-high teens on earnings and well below 15x EV/EBITDA. Rentomojo has a foot in each camp. Applying a blended 30–40x to normalised FY26 profit, or a mid-teens EV/EBITDA to a depreciation-heavy asset base, both point to an illustrative fair-value band in the ₹260–340 region — below the ₹384–404 ask. Credit a year or two of forward growth landing, and the top of that range stretches toward the band. In other words, the price does not misprice the business; it pre-pays for growth that still has to arrive.
Good company, good growth — good value?
On the three-part test, Rentomojo scores clearly on the first two. It is a good company: a category leader with a sticky, repeat-heavy subscriber base and rare, genuine profitability. It has good growth: 40%-plus revenue expansion with improving unit economics and a still-underpenetrated market. The value question is where reasonable investors will differ. On reported earnings the ~40x headline looks almost mainstream; on normalised earnings, and against the asset-heavy reality of the model, ~60x asks investors to underwrite years of continued compounding — and to do so while funding an investor exit rather than fresh growth.
None of that makes it a "bad" IPO or a "good" one; those are verdicts each investor must reach against their own horizon and price discipline. What it makes it is a quality business at a full price — the kind of listing where the debate is never about the company, only about the number. For a serious long-horizon investor, the more useful exercise than a listing-day guess is to decide what you would pay for that growth, and let the market come to you.
References & further reading
- Rentomojo Limited — Red Herring Prospectus, dated 3 September 2026 (Objects of the Offer; Financial Information; Basis for Offer Price)
- Redseer — Indian rental furniture market sizing (as cited in the RHP)
- chittorgarh.com/ipo/rentomojo-ipo/2971/ — issue structure, dates and indicative valuation
- screener.in — for post-listing financial updates once available
Keep reading
20 Sep 2026
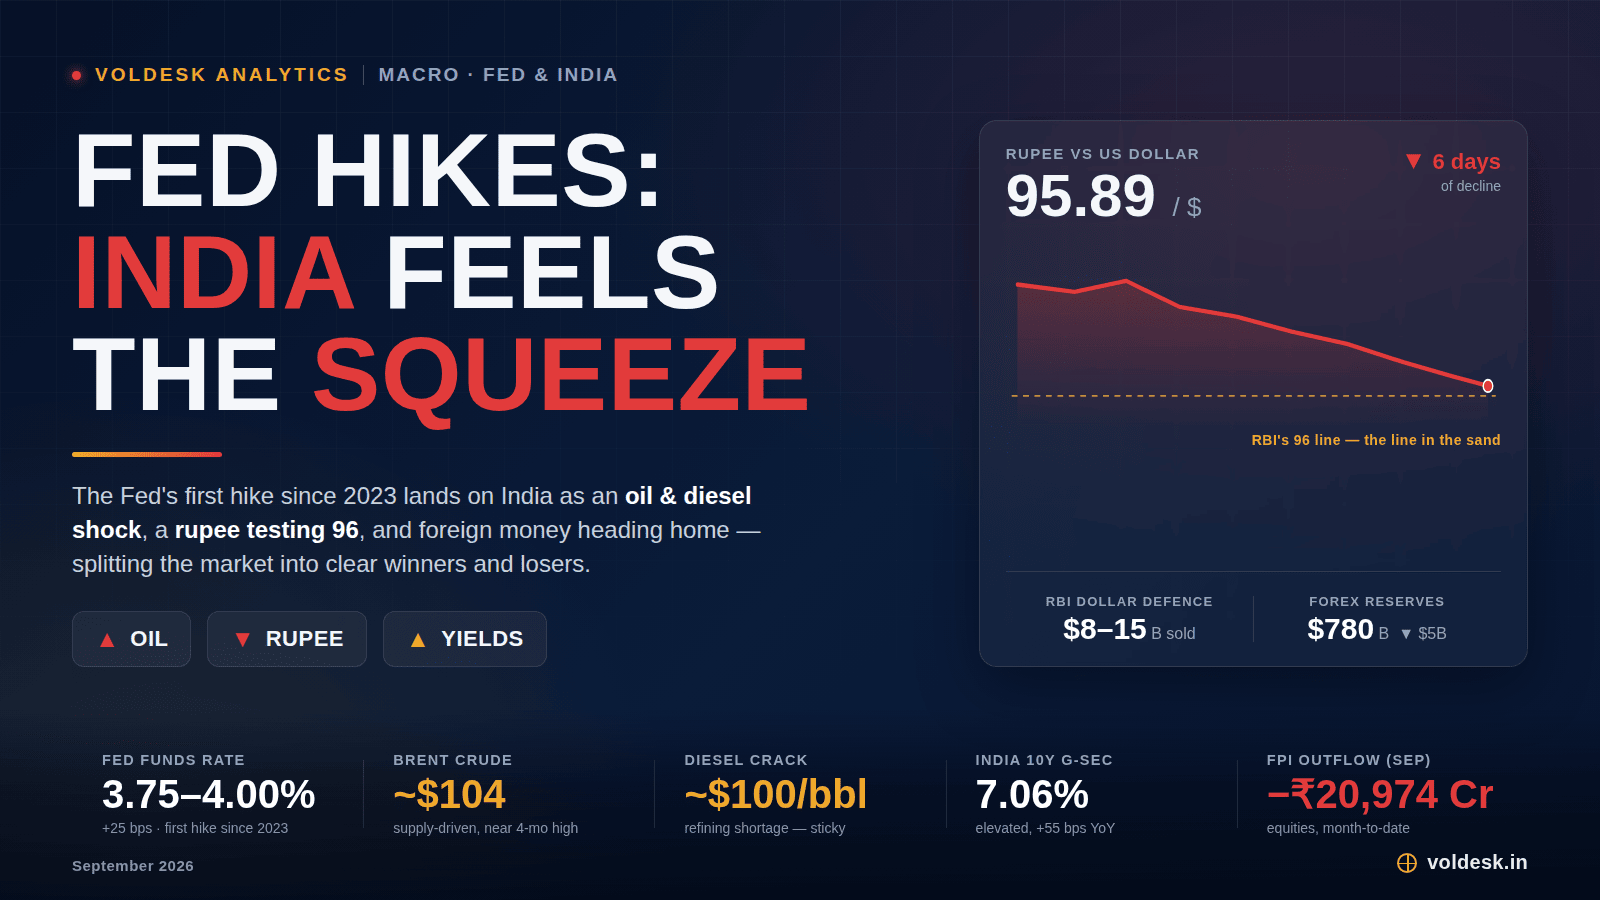
Fed Hikes: India Feels the Squeeze
On September 16, 2026, the Federal Reserve raised its target range by 25 basis points to 3.75% – 4.00% — its first hike since 2023. The trig…
09 Sep 2026
Tempsens: The Manufacturing-Leader Premium, Already Priced In?
Tempsens Instruments (India) priced its IPO at ₹300 — roughly 35x earnings — listed on 28 August 2026 and closed its first day at ₹586.65 , …
30 Aug 2026
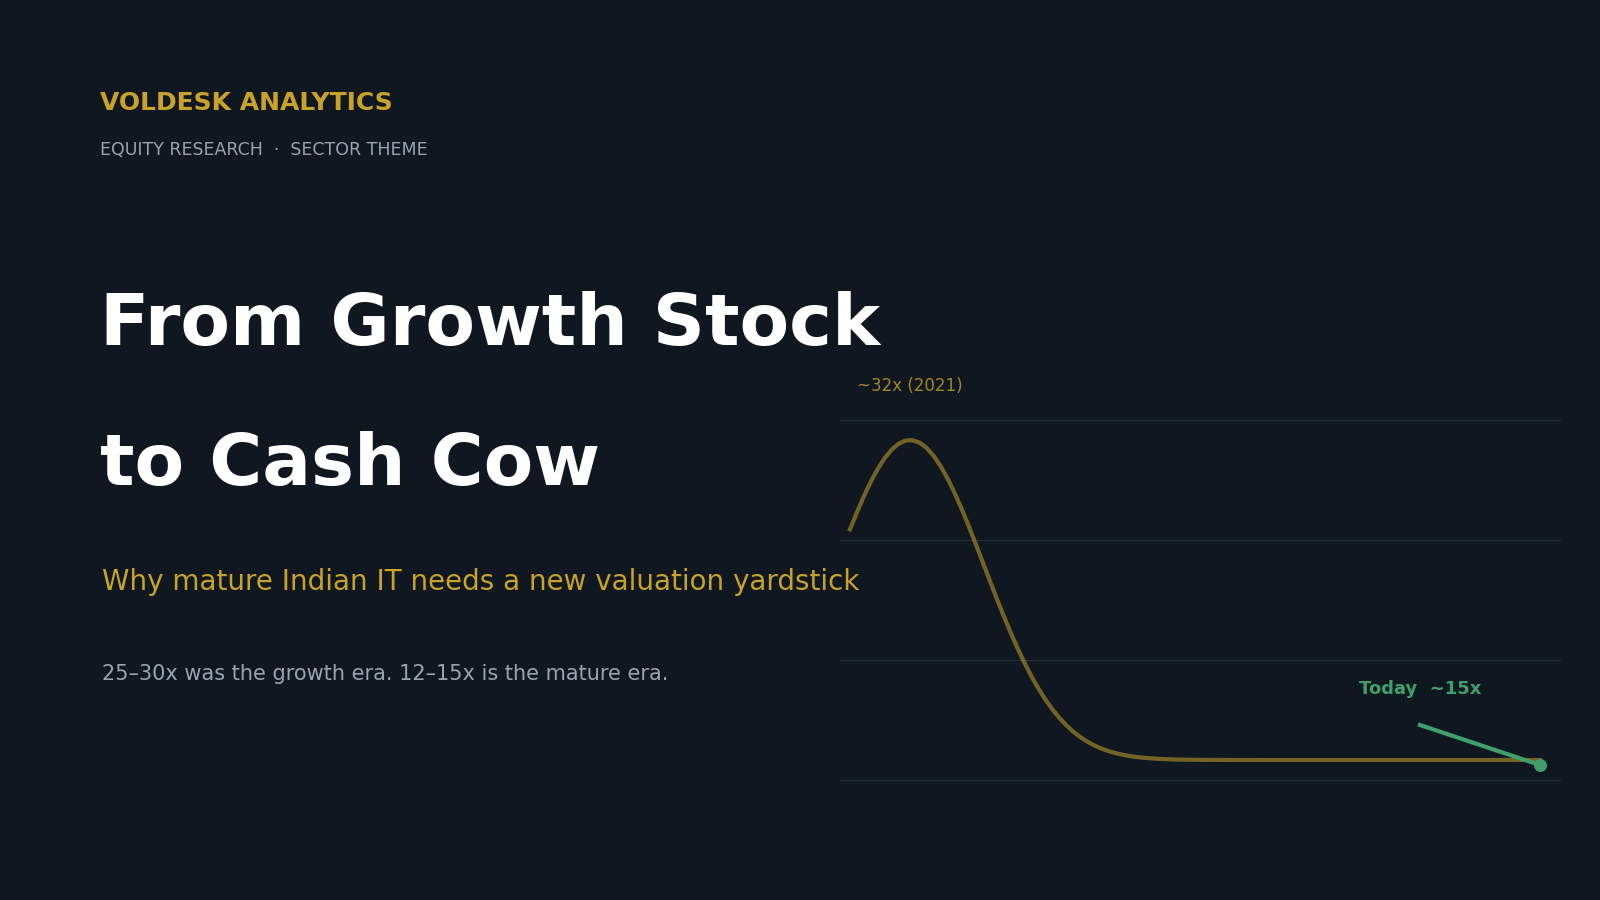
Indian IT: From Growth to Cash Cow
For fifteen years, Indian IT services was the market's dependable growth machine, and investors paid for it accordingly. Through most of the…
Disclosure — Educational market commentary only. Not a recommendation to deal in any security. Figures are drawn from the company prospectus and public sources as at the date of publication and may change. This article is for information and education only and does not constitute personalised advice. Investments in securities are subject to market risk; no returns are assured.